Across Ireland, Iarnród Éireann’s current investment programme points to a railway being reshaped in practical, place-specific ways rather than through any single headline scheme. Supported by the National Transport Authority and linked to Project Ireland 2040, the wider programme spans trains, track, signalling, stations and customer facilities. It sits within the National Development Plan and is presented as part of a broader response to growing transport demand, climate targets and the need for better public transport links between communities.
At network level, the ambition is considerable. Iarnród Éireann says investment will include up to 790 new train carriages, with up to 600 of those planned to be electric or battery electric. Alongside fleet renewal, there is continued spending on track, signalling and level crossings to increase frequency and improve journey times, as well as on new stations and upgrades to existing ones, with accessibility and car parking among the stated priorities. Further investment is also planned beyond the schemes already in progress.
What becomes clear when looking across the current portfolio is that these projects vary widely in scale and purpose. Some are focused on unlocking extra train movements on existing lines, others on creating entirely new transport hubs, while some are designed to resolve long-standing operational constraints. Together, they show a rail system being adapted for a different kind of use, with more frequent suburban services in growing urban areas, better interchange between modes and infrastructure that is more resilient and more accessible than it was previously.
Galway: Two Projects, One Direction
Oranmore Station
In Galway, two separate, but related strands of work illustrate that approach. At Oranmore Station, Iarnród Éireann has planning permission from Galway County Council and Galway City Council for works intended to allow more trains to operate between Galway and Athenry. The present constraint is straightforward: the Athenry to Galway line is currently single track, with no opportunity for trains travelling in opposite directions to pass each other. The planned intervention is equally direct, comprising a one kilometre section of double track at Oranmore Station and a new second platform measuring 185 metres.
That may sound like a modest change in engineering terms, but its operational effect is significant. Iarnród Éireann says the work will allow a doubling of train services calling at the station, bringing service levels to every 30 minutes in each direction. The project is part funded by the Department of Housing, Local Government and Heritage through the Urban Development and Regeneration Fund and part funded by the National Transport Authority, linking local rail improvements to wider housing and planning policy.
The station itself is also set to change in a more visible way. The new platform will sit to the north of the current one and will be reached through a new underpass beneath the railway. That underpass is intended not only for station access but also to provide a dedicated cycle route to lands north of the line. Stairs, a lift and an access ramp are included so that both platforms are accessible, while shelters, help points, customer information signs, lighting, CCTV and seating are all part of the scheme.
The reasoning behind the project extends well beyond the timetable. Iarnród Éireann says the improved station will support the proposed 1,000-unit residential development identified in the Garraun Urban Framework Plan, making it possible for that growth to be compact and sustainable, with public transport readily accessible. The scheme is also described as creating the opportunity for a transport hub serving both the station and the wider Garraun development. In policy terms, it is presented as aligning with the Climate Action Plan, NIFTI, the National Development Plan, the Galway County Development Plan and the Galway Metropolitan Area Strategic Plan, while the hoped-for shift towards rail is expected to reduce noise, emissions and local air pollution.
Progress at Oranmore has moved beyond planning. Advance enabling works began in 2024 and included trackside signalling activity as well as the relocation and modification of telecoms and signalling cables, all intended to prepare for the underpass installation and later main works. The first major construction phase was completed in October 2025, when contractor P&D Lydon installed the new pedestrian and cycle underpass during a planned rail possession weekend on the 11th and 12th of October. The next stage will deliver the remaining elements, including the new platform, the 1 km passing loop, the lift, ramp and stairs and a bridge deck replacement. That contract was tendered in late 2025, with works planned to start in the first half of 2026 and the overall project due for completion by the end of 2027.
Ceannt Station Redevelopment
Galway’s other major rail investment is far larger in urban terms. The redevelopment of Ceannt Station began at the start of 2024 and is funded by the Department of Housing’s Urban Regeneration and Development Fund together with the National Transport Authority. The project is framed around Ceannt’s central location, with Iarnród Éireann describing it as perhaps the best-located railway and bus station among Ireland’s major cities. The aim is to turn it into an expanded and integrated transport hub at the heart of Galway.
Here, the emphasis is on interchange, urban access and future capacity. The redeveloped station is intended to support modal shift towards public and active travel, lower emissions and improved city retail facilities, while also integrating improved rail and bus infrastructure with compact land use development, particularly the proposed Augustine Hill development south of the station. Accessibility is a recurring theme, with mobility-impaired passengers said to be prioritised through features including a Changing Places facility, and the plans also seek to improve circulation inside the station and reduce pressure on Station Road footpaths.
As a physical project, Ceannt Station’s transformation is substantial. Platform numbers are to increase from two to five, allowing for significantly expanded rail services in the future. A new southern entrance and façade will add customer facilities, retail units and toilets, while the existing train hall is to receive a new roof intended to make circulation and platform areas brighter and more welcoming. Renovation of the northern elevation also forms part of the plan, with track, resignalling, drainage and other infrastructure works needed to support the enlarged station. BAM Ireland is carrying out the work for Iarnród Éireann, with substantial completion expected by mid-2026. Throughout the programme, rail and bus services are due to continue, with temporary walking route changes communicated to customers beforehand.
Waterford: A Station Embedded in Urban Renewal
If Galway shows how rail is being used to shape urban growth and improve interchange, Waterford North Quays demonstrates how a station project can be embedded in a much wider redevelopment area. Waterford City and County Council is progressing the North Quays Strategic Development Zone on the north bank of the River Suir in the city centre. The zone is planned as a mixed-use development supported by transport infrastructure, with a new transport hub and railway station approximately 1 km east of the existing Plunkett Station. This new hub will be linked into the city by a sustainable transport bridge.
For the railway, that means more than simply building a replacement station. The project requires remodelling and upgrading of existing track and signalling, while rock face stabilisation works have already taken place at the existing station. It also aims to deal with existing flooding issues that currently restrict railway operations in Waterford. The scope includes a bridge over the railway at the transport hub with the station ticket hall and concourse built into it, a footbridge at the western end of the new station, two vehicular bridges over the railway and two more over the disused New Ross railway line.
The relocation of Plunkett Station to a new site approximately 1 km to the east involves new railway platforms, access stairs and lifts, storage facilities, offices and toilets, as well as a ticket desk, public toilets, a retail unit and related ancillary facilities. Around the station, there will be realignment and provision of double track, signalling works to support the new layout and the removal or decommissioning of the existing level crossing into the North Quays. Spring 2026 has been identified as the proposed opening date, subject to completion of construction and commissioning of the new track and signalling system.
Limerick: A New Station for Moyross
In Limerick, the focus is on a new local station with a regenerative purpose. Iarnród Éireann plans to build Moyross Station on the existing Limerick to Galway line, in what is described as the civic heart of Moyross. The project is intended to improve public transport links for a growing population and to connect the area not only with Limerick city centre but also with Galway, Cork, Dublin and beyond. It also aims to serve nearby destinations including Thomond Park, the TUS Gaelic Grounds, the Technological University of the Shannon and other educational and civic facilities.
Moyross is notable for the way it is tied into other transport plans. The new station is intended to integrate with Limerick City and County Council’s proposed University Avenue scheme, with BusConnects Limerick and with the proposed Limerick CycleConnects network. It is identified as one of the rail-based measures in the Limerick Shannon Metropolitan Area Transport Strategy 2040 and is also listed as an objective in the Limerick Development Plan 2022 to 2028. In that sense, the station is being advanced not as a stand-alone intervention but as part of a wider reshaping of movement through the city.
The emerging preferred option places the station to the rear of Corpus Christi Primary School and Moyross Community Enterprise Centre, with access adjacent to Corpus Christi Parish Church via Sarsfield Gardens and through Millennium Park. The proposed station would have a single platform on the southern side of the line, approximately 175 metres long and between 3 and 4.5 metres wide. Ticket vending machines, passenger information and public address systems and shelters are included, while the western entrance via Millennium Park would be open to pedestrians and provide a bike shelter area. The eastern entrance off Sarsfield Gardens would be for pedestrians only, and bicycle parking would be provided at both entrances.
The stated benefits are concrete and measurable. Approximate journey times are given as 11 minutes to Limerick Colbert, 15 minutes to Sixmilebridge, 32 minutes to Ennis and less than two hours to Galway. Iarnród Éireann also says that by 2043 almost 7,000 people will live within a 15-minute walk of the proposed station. Planning reached an important milestone in November 2025 when Limerick City and County Council issued a Decision to Grant Planning, and advance works were completed in December 2025. Procurement is expected to begin in spring 2026, funded by the National Transport Authority under the Department of Transport’s Pathfinder Programme.
Cork: The Largest Package of All
Cork, however, is where the broadest and most interconnected package of rail works is now under way. The Cork Area Commuter Rail programme forms a central part of the Cork Metropolitan Area Transport Strategy 2040 and is described by Iarnród Éireann as the largest ever investment in Cork’s rail network. It covers the heavy rail network linking Mallow, Cork, Cobh and Midleton and aims to increase capacity and frequency while adding new stations and, in time, electrification.
The programme is being delivered in phases. Phase 1 includes the Kent Station through platform, twin tracking between Glounthaune and Midleton and a signalling and communications upgrade. Phase 2 turns to expansion, with proposals for eight new stations, upgrades to three existing stations, a new depot and full electrification of the Cork rail network. The longer-term goal is an electrified high-frequency rail system with services targeted every 10 minutes.
Phase 1
Phase 1 is the further advanced of the two, with construction already complete on one of its three elements. Each element addresses a distinct part of the same operational problem: removing the bottleneck at Kent Station, adding capacity on the Midleton line and upgrading the signalling infrastructure that underpins both.
Kent Station Through Platform
At Kent Station, new platforms 5b and 6 were designed to remove an operational bottleneck that had long constrained through running. Before the works, most services from Mallow, Midleton and Cobh terminated at Kent, requiring passengers to change if continuing their journey. The new through platforms allow commuter trains to run from Mallow through Kent and onward to Midleton or Cobh without terminating. Construction was completed in March 2025 and the platforms entered service in April 2025, with the official opening attended by Taoiseach Micheál Martin. Works included a 220-metre-long, 6 metre wide double-sided extension to Platform 5, track reconfiguration, retaining wall works and reinstatement of eastern access to the station subway from Platform 5.
Glounthaune to Midleton Twin Track
Further east, the Glounthaune to Midleton Twin Track project covers approximately 10 km from Cobh Junction to Midleton. Its main purpose is the installation of a second track along the full length of the line, together with sidings and turnaround facilities at Midleton, bridge and level crossing modifications, signalling alterations and associated civil works. The project is intended to support an increase from the current 30-minute service to as frequent as every 10 minutes in future, alongside the new through platform, signalling works and a new fleet. A Railway Order was granted by An Coimisiún Pleanála in November 2023, BAM Civil Ltd won the civil works contract worth €29.5 million and construction began in autumn 2024. Completion is expected in late 2026.
Signalling and Communications Upgrade
The signalling and communications upgrade is the less visible but equally necessary part of the same package. It involves new cabling and containment between Mallow and Cobh or Midleton, new signal poles and trackside signalling equipment, power supply points and equipment buildings. It also includes upgrading the Train Protection System in the Cork area to ETCS Level 1 to meet European railway standards. Alstom was awarded the design and build contract in June 2023 and construction started in January 2024, with the works scheduled to finish by the third quarter of 2026. Iarnród Éireann says these upgrades will make possible the future increase to 10-minute frequencies while improving reliability and allowing eventual central management through the new National Train Control Centre at Heuston Station when that becomes operational.
Phase 2: New Stations, New Depot
While Phase 1 continues through to completion, Phase 2 is still being shaped through public consultation. The scale of this second phase is particularly striking, with proposals for eight new stations: Blarney/Stoneview, Monard, Blackpool/Kilbarry, Tivoli, Dunkettle, Ballynoe, Carrigtwohill West and Water-Rock. Mallow, Midleton and Cobh are to be upgraded for accessibility and future capacity. Strategic Park and Ride sites are proposed at Blarney/Stoneview and Dunkettle, each expected to provide between 400 and 600 spaces, while local Park and Ride sites would provide up to 100 spaces. A new depot is also planned at Ballyrichard More, east of Carrigtwohill, to support maintenance and stabling of the future fleet.
The first of two non-statutory consultations on the Emerging Preferred Option took place from the 18th of June to the 23rd of July 2025. Feedback from that process is intended to inform further design development before a second consultation on the Preferred Option. Only after that will a Railway Order application be prepared, followed by the statutory consultation period run by An Coimisiún Pleanála.
The Level Crossings Project
Also on the Cork to Dublin main line, a significant planning milestone was passed in July 2024 for a related scheme. The Cork Line Level Crossings Project is concerned with seven manned public road level crossings between Limerick Junction and Mallow, all within a 24 km section spanning Counties Cork and Limerick. The crossings are at Fantstown, Thomastown, Ballyhay, Newtown, Ballycoskery, Shinanagh and Buttevant. Iarnród Éireann says the objective is to identify the best approach to removing or upgrading them in order to improve safety for nearby residents and support a more efficient rail service. A Railway Order was lodged with An Coimisiún Pleanála, an oral hearing took place in September 2022 and approval was granted in July 2024 after a process lasting over 37 months.
The Broader Picture of Rail Investment in Ireland
Taken together, these schemes show how rail investment in Ireland is being pursued through many linked interventions rather than one simple expansion. Some projects address capacity on single-line sections, others rebuild city stations as transport hubs and others still modernise the systems that sit behind daily operations. What unites them is a recurring set of themes: higher frequencies, better interchange, improved accessibility, support for housing and urban development and a stated move towards lower-emission travel. The exact pace of delivery will continue to depend on procurement, planning and construction, but the direction of travel is already clear.
Inspired by Switzerland’s world-renowned rural public transport system, Mini Switzerland is a national demonstrator project aimed at transforming how people travel in rural Britain, using Derbyshire’s Hope Valley as its real-world testing ground. The project, developed by Hope Valley Climate Action with funding from the Foundation for Integrated Transport, proposes building a fully integrated network of buses and trains operating to a regular clock-face timetable, with services running at the same times each hour, every hour, from early morning until late at night, seven days a week. Buses would connect seamlessly with trains at key interchange hubs at Bamford, Hope and Edale stations, ticketing would be simplified into a single unified product valid across all operators and modes, and every village along the corridor would be served at least hourly.
The Hope Valley is considered an ideal location because it already has an hourly rail service linking Sheffield and Manchester, a mix of villages, schools, workplaces and visitor attractions, and millions of annual visitors to the Peak District National Park, nearly all of whom currently arrive by car. Around one in three households in both Sheffield and Manchester has no access to a car, meaning large parts of the National Park are effectively unreachable for a significant proportion of the urban population.
The project requires modest capital investment of around one million pounds in infrastructure improvements such as hub upgrades, bus stop enhancements and signage, alongside estimated annual operating costs of around four million pounds in its first full year, falling as ridership grows. Crucially, the demonstrator is designed to generate structured, measurable evidence on passenger behaviour, operational reliability, ticketing uptake and demand growth over a five-year period, providing a practical model that rural authorities, National Parks and combined authorities across Britain can study, adapt and replicate.
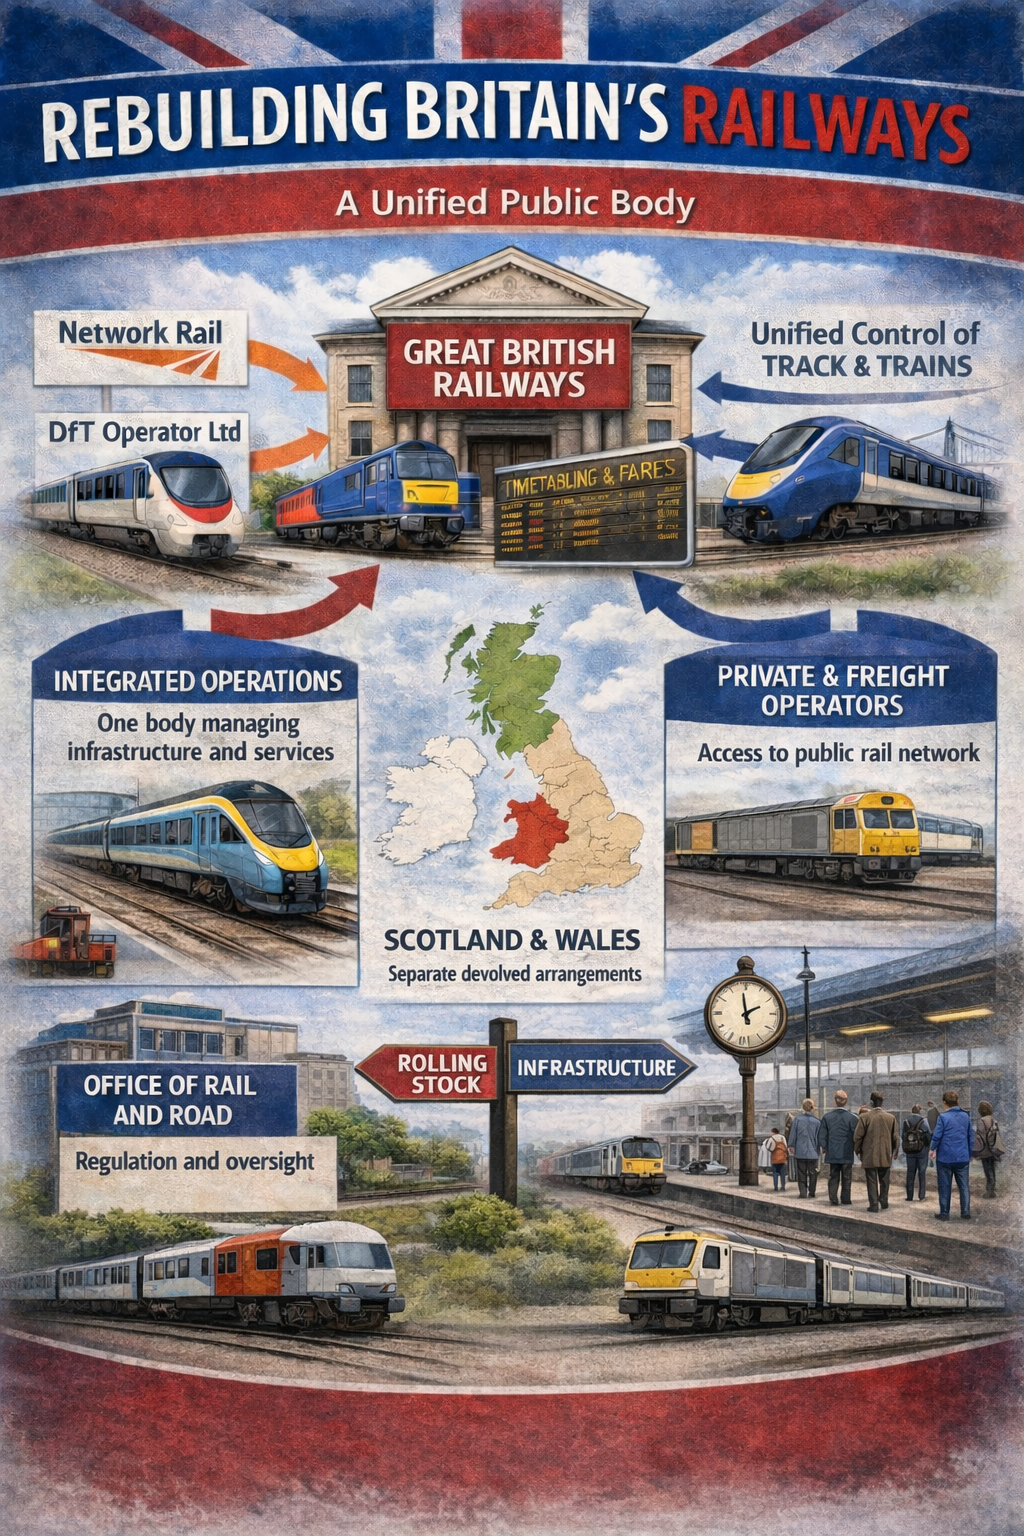
The creation of Great British Railways represents the most fundamental restructuring of Britain’s railway since privatisation in the 1990s. GBR is intended to unify functions that have been split across organisations since privatisation, bringing together infrastructure, timetable planning and fares alongside the contracted passenger railway. Where DfT Operator Ltd exists as a temporary holding structure for nationalised operators, Great British Railways is designed to be permanent, absorbing Network Rail, DfT Operator Ltd and key functions from the Department for Transport into a single public body responsible for running Britain’s railway.
The establishment of GBR has been a long time coming. Plans were first announced in 2021 under the previous Conservative government, following the Williams-Shapps Review which called for radical reform of the fragmented railway system. However, progress stalled, and by 2024 little had been achieved beyond the creation of a shadow organisation. The election of the Labour government in July 2024 gave the project renewed momentum, with the Passenger Railway Services (Public Ownership) Act 2024 receiving Royal Assent in November and a Railways Bill introduced to Parliament in November 2025. This legislation, once it becomes law, will formally establish Great British Railways and set out its powers and responsibilities.
GBR is expected to be fully operational during the 2027 to 2028 period, depending on the timing of legislation and implementation. The government has promised to base the organisation outside London to promote economic growth and skills in a region outside the capital. In February 2022, the Department for Transport launched a public consultation for the location of GBR’s headquarters, though a final decision has not yet been announced. Laura Shoaf chairs the shadow Great British Railways, preparing for the organisation’s formal establishment.
The GBR Model: Reunifying Track and Train
At the heart of the GBR model is the reunification of track and train. Since privatisation, the railway has been split between infrastructure management (Network Rail) and passenger operations (train operating companies), with coordination handled through contracts, access agreements and regulatory oversight. This separation has been widely criticised for creating fragmentation, misaligned incentives and operational inefficiencies. Delays caused by infrastructure problems become the train operator’s responsibility for compensation purposes, even though the operator has no control over the track. Timetable planning requires coordination between multiple organisations with different commercial interests. Investment decisions on infrastructure and rolling stock are often made separately, leading to mismatches and missed opportunities.
GBR is designed to solve these problems by bringing track and train under unified management. It will absorb Network Rail’s functions, becoming the infrastructure owner and manager for most of Great Britain. This means GBR will own and maintain the track, signalling, stations and other fixed assets, employing the engineers, signallers and infrastructure staff who keep the physical railway running. At the same time, GBR will absorb the train operating companies currently held by DfT Operator Ltd, bringing passenger services under the same organisational roof. Staff who currently work for LNER, Northern, South Western Railway and the rest will become GBR employees, operating trains under what is expected to be a unified brand.
This unified structure is intended to create a single point of accountability. When a train is delayed, GBR will be responsible for both the infrastructure that caused the delay and the service affected by it. When timetables are planned or investment is considered, the same organisation will make decisions about track capacity and train operations, infrastructure and rolling stock together rather than in isolation. The ambition is to create what the government calls a “directing mind” for the railway, an organisation with the authority and capability to manage the system as a coherent whole.
Timetabling, fares and ticketing will also be brought under GBR’s control. Currently, timetable planning involves negotiations between train operators, Network Rail and the Department for Transport, with the Rail Delivery Group coordinating industry-wide ticketing and some commercial activities. Under GBR, timetabling will become an internal planning exercise rather than a negotiation between separate organisations, potentially allowing for more efficient use of capacity and better integration between services. Fares policy and ticketing systems will also be managed centrally, with the potential for simpler fare structures and more integrated ticketing, though this will depend on political decisions about pricing and subsidy.
The Rail Delivery Group, which has coordinated some industry-wide functions under the current fragmented model, will be absorbed into GBR, along with relevant parts of the Department for Transport that currently manage contracts with train operators. This consolidation is intended to reduce duplication and streamline decision-making, concentrating railway management expertise within a single organisation rather than spreading it across multiple bodies.
Devolution Within GBR
While GBR is intended to be a Great Britain-wide organisation, devolution means that Scotland and Wales will have different relationships with it than England. Infrastructure ownership and strategic control do not map neatly onto each other, and the model for GBR has been designed to accommodate the constitutional realities of devolution while maintaining a single infrastructure owner.
In Scotland, the likely model under GBR mirrors the current arrangement with Network Rail. Infrastructure will be legally owned by GBR, but strategic control will remain devolved. Scottish Ministers, working through Transport Scotland, will specify funding, investment priorities and performance requirements, and GBR Scotland will function as a distinct business unit shaped by those requirements. This maintains the substance of devolution while avoiding the complexity and cost of splitting infrastructure ownership along the England-Scotland border.
The practical effect is that GBR Scotland will operate day-to-day infrastructure management under strategic direction from the Scottish Government, while train services in Scotland will continue to be run by ScotRail, which is owned by the Scottish Government and will not be absorbed into GBR. Caledonian Sleeper, also owned by the Scottish Government, will similarly remain separate. GBR’s role in Scotland will therefore be limited to infrastructure, with passenger services remaining under Scottish control. Coordination between GBR and the Scottish Government will be necessary for cross-border services and for managing the interface between infrastructure and operations, but the expectation is that this will be handled through established mechanisms rather than requiring major institutional innovation.
In Wales, infrastructure devolution has been more limited. Most rail infrastructure in Wales is owned and managed by Network Rail, with control largely retained by the UK Department for Transport. Welsh Government’s main lever is over train services through Transport for Wales Rail, which has been in public ownership since February 2021 and will not be absorbed into GBR. Under the GBR model, most infrastructure in Wales would be expected to be owned and operated by GBR, while Welsh Government continues to control Transport for Wales Rail services.
A notable exception is the Core Valleys Lines around Cardiff, which were transferred fully to Welsh Government ownership in 2020, creating a pocket of infrastructure that sits outside the main Network Rail ownership model. These lines are expected to remain under Welsh Government ownership under GBR, meaning there will be a small part of the Welsh rail network where both infrastructure and services are devolved. For the rest of Wales, GBR would own and operate infrastructure while Welsh Government controls train services, requiring coordination between the two organisations for timetabling, investment and operational matters.
England is the most straightforward case. GBR is expected to bring together infrastructure and most passenger operations along with timetable and ticketing responsibilities, creating a fully integrated model where track and train are managed by the same organisation. There are no devolution considerations in England, and the expectation is that GBR will exercise direct control over both infrastructure and operations, subject to funding and policy direction from the UK government.
What Stays Outside GBR
Not every part of Britain’s railway will be absorbed into Great British Railways. Open access passenger operators and the freight sector are expected to remain in private ownership, operating as commercial businesses on GBR-managed infrastructure.
Open access passenger operators such as Lumo, Hull Trains and Grand Central operate outside the contracted system entirely. They are private companies that run services on the national network without government contracts and without operating subsidy, taking commercial risk and relying on ticket revenue. Lumo, owned by FirstGroup, began running low-cost services between London King’s Cross and Edinburgh in 2021, offering a budget alternative to LNER’s contracted services on the same route. Hull Trains, also owned by FirstGroup, has operated between London King’s Cross and Hull since 2000. Grand Central, owned by Arriva Group, has run services since 2007, linking London with Sunderland and Bradford.
These operators pay track access charges to use the network and fit into the timetable through an approvals process that considers capacity, performance impacts and the effect on publicly funded services. Under GBR, the expectation is that they will continue to exist as private businesses, with GBR acting as the infrastructure owner and timetable coordinator. The Office of Rail and Road will remain central to regulating access and preventing unfair discrimination, ensuring that GBR as infrastructure manager does not favour its own train services over open access operators or create barriers to market entry.
The government has indicated that open access operators will continue to have a role where they “add value and capacity to the network”, suggesting that the policy is to maintain competition on routes where it can operate without undermining publicly funded services. The regulatory framework will be crucial here, as GBR will be both the infrastructure manager and the dominant passenger operator, creating potential conflicts of interest that the ORR will need to manage.
Freight sits even more clearly outside the passenger ownership debate. Britain’s rail freight sector has been fully privatised since the 1990s and is expected to remain so under GBR. Freight operators pay access charges to use the network and continue to run commercially, carrying goods ranging from intermodal containers and aggregates to automotive parts and specialist loads. The main companies include DB Cargo UK, owned by Deutsche Bahn, Freightliner owned by Brookfield Asset Management, GB Railfreight owned by Infracapital and Colas Rail UK owned by the Colas Group. Direct Rail Services is a notable exception in ownership terms, being owned by the UK Nuclear Decommissioning Authority, but it remains separate from GBR and operates specialist traffic including nuclear material as well as other freight and support services.
Under a GBR model, freight operators will continue to run trains while GBR manages the infrastructure, allocates capacity and coordinates timetables. The government has indicated that GBR will have a statutory duty to promote rail freight, including a rail freight growth target, recognising the sector’s importance for decarbonisation and for moving goods efficiently. This is intended to ensure that freight is not squeezed out as GBR prioritises its own passenger services, though the practical balance between passenger and freight access will depend on capacity constraints, operational priorities and regulatory oversight.
Rolling stock ownership is another area that will remain outside GBR. The trains themselves are owned by rolling stock leasing companies (ROSCO’s), private firms that purchase trains and lease them to operators. This arrangement has continued throughout privatisation and is expected to continue under GBR. The government has indicated that nationalising the ROSCO’s would be prohibitively expensive, and that leasing provides flexibility for operators to adjust their fleets as demand changes. GBR will therefore lease trains from ROSCO’s rather than owning them outright, maintaining a significant role for private capital in the railway even as passenger operations and infrastructure are brought into public ownership.
Managing a Mixed Railway
The challenge for GBR will be managing a railway where infrastructure and most passenger services are publicly owned, but where private operators continue to run some passenger services and all freight. This requires a framework for allocating track capacity, planning timetables and resolving disputes that balance public service obligations with the access rights of commercial operators.
Track access rights are the foundation of this framework. Contracted passenger services operated by GBR will form the core of the timetable because they are tied to public service obligations and detailed specifications about frequency, calling patterns and service quality. These services are the reason the infrastructure exists in its current form, and they carry the vast majority of passengers. Freight operators also have firm access rights reflecting their economic role and their importance for decarbonisation, though their paths are often planned around peak passenger periods where possible due to the operational constraints created by slower trains with different performance characteristics.
Open access passenger services have access rights too, but these are more conditional and must be approved with regard to network capacity and impacts on public service operations. The approvals process considers whether an open access service would abstract revenue from publicly funded services (the “not primarily abstractive” test) and whether it would cause operational problems or require infrastructure investment that would not be justified by the benefits. This means open access operators face higher barriers to entry than they would in a fully commercial market, but the principle remains that access should be available where it does not undermine public service or create unmanageable operational problems.
Timetable construction under GBR will typically proceed in layers, beginning with infrastructure constraints and engineering access (the times when the track needs to be closed for maintenance or renewal), then building core passenger service patterns, then integrating freight paths and finally fitting open access services where capacity allows. This hierarchy reflects policy priorities, with publicly funded passenger services and infrastructure maintenance taking precedence, followed by freight (which has statutory protection) and then commercial passenger services.
Disputes over access are shaped by contractual rights and regulatory oversight, with the Office of Rail and Road providing a safeguard to ensure decisions are not arbitrary and that competition and freight needs are protected even where the infrastructure manager is closely linked to the dominant passenger operator. The ORR has powers to investigate complaints, require changes to access arrangements and impose penalties for anticompetitive behaviour. This regulatory backstop is crucial for maintaining confidence in the system, particularly for freight operators and open access passenger operators who will be dealing with an infrastructure manager that is also their competitor.
The ORR will also have broader responsibilities under GBR, including setting the framework for infrastructure funding through five-year control periods (similar to the current model with Network Rail), monitoring performance and efficiency, and ensuring that investment decisions are justified and well-managed. This provides a degree of independent oversight over GBR’s infrastructure activities, reducing the risk that political pressures or operational short-termism lead to underinvestment or poor decision-making.
Integration and Permanence
Great British Railways represents a fundamental shift in how Britain’s railway is organised. Where privatisation created fragmentation and DfT Operator Ltd has provided a temporary holding structure for nationalised operators, GBR is designed to be a permanent, integrated organisation responsible for both infrastructure and passenger operations. The ambition is to create a railway that works as a coherent system rather than a collection of separate businesses, with unified planning, clear accountability and the ability to make long-term decisions about investment and service development.
The success of GBR will depend on how effectively it manages the tensions inherent in its structure. It must balance public service obligations with commercial efficiency, accommodate devolution while maintaining a unified infrastructure, and provide access for private operators while prioritising publicly funded services. It must deliver better performance and value for money than the current fragmented system, while avoiding the pitfalls that led to the decline of British Rail before privatisation.
The result will be a railway that may look familiar to passengers in many respects, with trains running on the same routes and serving the same stations, but with a fundamentally different organisational structure behind the scenes. Track and train will be managed by the same organisation for the first time in three decades, with the potential for better integration, clearer accountability and more coherent long-term planning. At the same time, devolved operators in Scotland and Wales will remain outside GBR’s passenger operations, and privately run open access and freight operators will continue to operate on the network, creating a mixed model that reflects both the political realities of devolution and the practical need to maintain competitive access for non-GBR operators.
Whether this model delivers the improvements promised by its advocates will become clear over the coming years as GBR takes shape and begins to reshape Britain’s railway.
Britain’s passenger railway has been moving through a prolonged period of structural change, with the old franchising model replaced by management-style contracts and an increasing share of train services brought into public ownership. In the middle of this sits DfT Operator Ltd, a government-owned company that has shifted from being an emergency backstop to becoming the main holding structure for nationalised passenger operators in England. While many passengers will notice little beyond the familiar brand names on trains and stations, the corporate and governance arrangements behind those brands have been changing at pace.
DfT Operator Ltd is wholly owned by the UK government through the Secretary of State for Transport. Its role is to own and oversee passenger train operating companies that have been brought into public ownership, ensuring services continue to run and that there is a clear management structure for operators that are no longer privately run. What began as a contingency arrangement has become a central pillar of rail reform, and DfT Operator Ltd’s purpose has expanded into something more like a temporary national operating group for England, ahead of the planned creation of Great British Railways.
Origins and Legal Framework
The company began life in 2018 under the name DfT OLR Holdings Limited, created primarily to support the government’s “operator of last resort” function. The phrase “operator of last resort” explains the original logic. If a private franchise collapsed, was terminated or could not continue, the government needed a mechanism to take over quickly so that timetables, staffing and safety-critical operations could continue without interruption. From a passenger perspective, this kind of transfer is designed to be as quiet as possible. Trains still run, tickets remain valid and the public-facing brand often stays the same. Behind the scenes, however, the legal company running those trains changes ownership, with DfT Operator Ltd becoming the parent body responsible for governance and oversight.
In 2024 the company was renamed DfT Operator Limited, reflecting a broader shift in policy where public ownership is no longer presented only as a fallback when an operator fails, but as an increasingly standard destination as contracts end and the railway is reorganised. Over time, the franchising system has ended and the newer National Rail Contracts have tended to place more revenue and risk with government, making the step into direct ownership less of a leap than it once appeared. As a result, DfT Operator Ltd’s portfolio has grown considerably.
Part of understanding this landscape is recognising the difference between the brand passengers see and the legal entity behind it. Brands like LNER or Northern are what appear on trains, websites and station signs, but the companies that hold licences, employ staff and sign contracts are legally constituted firms such as London North Eastern Railway Limited and Northern Trains Limited. DfT Operator Ltd sits above these operating companies through a corporate structure that includes intermediate holding and management subsidiaries used for governance, financial structuring and liability separation.
Among the companies in this layer are Train Operating Company Holdings Limited, DfT Operator Railways Limited and DfT Operator Management Limited. There are also intermediate parents linked to particular operators, including London North Eastern Railway Holdings Limited and Northern Trains Holdings Limited. These names rarely appear in public discussion, but they matter for how the system is administered and how accountability is arranged.
The Transfer Programme: Chronology
The most prominent early example of a transfer into public ownership under this structure was London North Eastern Railway, which took over East Coast Main Line services on 24th June 2018. LNER replaced Virgin Trains East Coast after franchise failure, and it has since become one of the best-known government-owned operators, running long-distance trains connecting London with major centres such as York, Newcastle, Edinburgh, Leeds, Aberdeen and Inverness. The LNER transfer set the template for what would follow, demonstrating that services could continue seamlessly under public ownership while the railway’s longer-term future was decided.
The next major transfer followed on 1st March 2020 when Northern Trains entered public ownership, bringing a vast regional network across Northern England under DfT Operator Ltd’s control. This was a significant expansion in scale, taking in a complex web of local services across cities, towns and rural areas from the Humber to Cumbria. Northern’s transfer reinforced the pattern established by LNER: public ownership as a practical response to franchise difficulties rather than an ideological statement.
The pace of change continued into the early 2020s. SE Trains, the legal company behind the Southeastern brand serving London, Kent and parts of East Sussex including Highspeed services from St Pancras, transferred in October 2021. TransPennine Trains, operating TransPennine Express services connecting key cities across Northern England and into Scotland, followed on 28th May 2023. Each transfer reinforced the idea that DfT Operator Ltd was no longer simply an emergency stand-in but the main mechanism for keeping operators running while the industry’s long-term shape was decided.
In December 2025, Alex Hynes was appointed as CEO of DfT Operator Limited, taking over from Robin Gisby who had overseen the company through its earlier expansion. Hynes assumed leadership as the company prepared for its largest transfers yet, including the integration of Govia Thameslink Railway scheduled for May 2026.
The year 2025 marked a decisive acceleration in the transfer programme. In July 2024, the Labour Party won the general election with a manifesto commitment to renationalise the railways, and the Passenger Railway Services (Public Ownership) Act 2024 received Royal Assent in November. This legislation allowed passenger rail services to be returned to state control without requiring the purchase of private contracts, fundamentally changing the context in which DfT Operator Ltd operated. Public ownership was now policy rather than contingency.
Several further transfers were confirmed in quick succession, broadening the footprint of public ownership into some of the busiest commuter territory in the country. South Western Railway transferred on 25th May 2025, taking into public ownership an operator that runs from London Waterloo across a large part of the south west of England, linking destinations such as Southampton, Bournemouth, Portsmouth and Exeter and serving one of the most heavily used commuter networks in Europe.
c2c Rail, known for services between London Fenchurch Street and Essex destinations including Southend and Tilbury, transferred on 20th July 2025. Greater Anglia, operating across the East of England and serving places such as Norwich, Cambridge, Stansted Airport and Ipswich, transferred on 12th October 2025, bringing with it a network that had been recently modernised with a new train fleet.
The sequence continued into 2026. West Midlands Trains transferred on 1st February 2026, bringing the West Midlands Railway and London Northwestern Railway brands into public ownership. These services link London Euston with Birmingham, Liverpool and Crewe and also provide extensive regional coverage around Birmingham. Taken together with earlier transfers, this meant that by February 2026, eight of the fourteen English operators were already owned by DfT Operator Ltd, a significant change from a system that for years was framed around private operation under franchise agreements.
Alongside the list of operators already in public ownership, the government has also set out a programme for bringing remaining operators across. A particularly significant forthcoming transfer is Govia Thameslink Railway, confirmed to move on 31st May 2026. GTR is the largest operator in Britain and runs Thameslink, Southern, Great Northern and Gatwick Express, meaning it covers a large portion of London and the South East commuter railway and includes major airport links. The scale and complexity of this network means its transfer is a milestone in the nationalisation programme, not just another incremental addition.
Beyond GTR, further transfers have been confirmed as part of the programme even if final dates were not set out in the same way. Chiltern Railways, operating services from London Marylebone towards Birmingham and across parts of Buckinghamshire and Oxfordshire, has been identified in the next phase. Great Western Railway, which runs major intercity and regional services from London Paddington to Bristol, Cardiff and South Wales as well as routes into Devon and Cornwall, has also been confirmed in the programme. Avanti West Coast, operating intercity services on the West Coast Main Line between London and destinations including Birmingham, Manchester, Liverpool and Glasgow, has been identified as expected to transfer before the completion of the programme. CrossCountry, which provides long-distance links between regional cities without going through London, has also been identified as part of the remaining set expected to transfer by the end of the programme.
The overall stated direction is that transfers occur as contracts expire and that the process is expected to complete by October 2027.
How DfT Operator Ltd Works
From a passenger perspective, the transfer of an operator into DfT Operator Ltd is designed to be as seamless as possible. Trains continue to run on the same timetables, tickets remain valid, station facilities stay open and staff uniforms typically remain unchanged, at least initially. The public-facing brand is often retained, meaning that passengers boarding a Northern or LNER train see the same branding they would have seen under private operation. This continuity is deliberate. The Department for Transport is keen to avoid the kind of disruption that can accompany major organisational change, and the operational priority is to maintain service levels while ownership structures shift.
Behind the scenes, however, significant changes occur. The legal entity that holds the operating licence, employs staff and contracts for services changes hands. Management reporting lines shift, with operators now accountable to DfT Operator Ltd and through it to the Department for Transport rather than to private shareholders. Financial structures change too, with revenue and cost risk increasingly sitting with government rather than private operators. This reflects the broader trend under National Rail Contracts even before transfer, where the franchising model’s commercial risk has already been substantially removed.
DfT Operator Ltd functions as a holding company rather than an operational railway manager. It owns the train operating companies, provides governance and oversight, and ensures that performance standards are met. Day-to-day management of train services, staff and customer-facing operations remains with the individual operators, which retain their own management teams, depots, control centres and operational structures. The model is one of oversight and strategic direction rather than direct management from the centre.
The Limits of DfT Operator Ltd
DfT Operator Ltd’s remit is confined to England and to operators contracted with the Department for Transport. This means there are significant parts of Britain’s railway that sit outside its scope and will continue to do so.
Devolution means that Scotland and Wales have their own public ownership arrangements. ScotRail, Caledonian Sleeper and Transport for Wales Rail are already publicly owned, but not by DfT Operator Ltd and not by the Department for Transport. ScotRail is owned by the Scottish Government through Scottish Rail Holdings, with ScotRail Trains Ltd in public ownership since 1st April 2022. Caledonian Sleeper is also owned by the Scottish Government through Scottish Rail Holdings, transferring into public ownership in June 2023, and although its services run to London, it is treated as a devolved Scottish operation. Transport for Wales Rail Ltd is owned by the Welsh Government through Transport for Wales and has been in public ownership since February 2021. These operators are not expected to be absorbed into DfT Operator Ltd and they will remain under the control of their respective devolved governments.
An important nuance in the current official sequence is that East Midlands Railway, which runs from London St Pancras to cities including Nottingham, Derby and Sheffield, was not included in the confirmed transfer sequence described in the same terms as GTR, Chiltern, GWR, Avanti and CrossCountry. That absence does not necessarily indicate a permanent exception, but it does mean that the operator has not been formally scheduled in the way others have been in the programme described above. The reasons for this remain unclear, and it is possible that East Midlands Railway could be added to the programme at a later stage.
Not every operator on Britain’s railway fits into the passenger public ownership programme, and this is where open access and freight provide important context. Open access passenger operators such as Lumo, Hull Trains and Grand Central operate outside the contracted system entirely. They are private companies that run services on the national network without government contracts and without operating subsidy, taking commercial risk and relying on ticket revenue. Lumo, owned by FirstGroup, began running low-cost services between London King’s Cross and Edinburgh in 2021. Hull Trains, also owned by FirstGroup, has operated between London King’s Cross and Hull since 2000. Grand Central, owned by Arriva Group, has run services since 2007, linking London with Sunderland and Bradford. These operators pay track access charges and fit into the timetable through an approvals process, but they are not part of DfT Operator Ltd and are not scheduled for nationalisation.
Freight sits even more clearly outside the passenger ownership debate. Britain’s rail freight sector has been fully privatised since the 1990s and is expected to remain so. Freight operators also pay access charges to use the network and continue to run commercially. The main companies include DB Cargo UK, owned by Deutsche Bahn, Freightliner owned by Brookfield Asset Management, GB Railfreight owned by Infracapital and Colas Rail UK owned by the Colas Group. Direct Rail Services is a notable exception in ownership terms, being owned by the UK Nuclear Decommissioning Authority, but it remains separate from DfT Operator Ltd and operates specialist traffic including nuclear material as well as other freight and support services.
DfT Operator Ltd as Transition
DfT Operator Ltd is best understood as a transitional structure. It exists to hold and manage operators in public ownership before Great British Railways is fully created and able to absorb them into a single national framework. On the basis of the programme described above, most operators are expected to have transferred into DfT Operator Ltd by the end of 2027, with DfT Operator Ltd itself likely to be absorbed into GBR during the 2027 to 2028 period, depending on the timing of legislation and implementation.
This transitional status shapes how DfT Operator Ltd operates and how it is perceived. It is not presented as a permanent feature of the railway landscape but as a temporary holding structure that will eventually be superseded. This explains why branding remains operator-specific rather than unified under a DfT Operator Ltd identity, and why operational structures remain largely unchanged from the franchise era. The expectation is that more fundamental restructuring will occur once Great British Railways is established and able to take a comprehensive view of the passenger railway as a whole.
Viewed as a whole, DfT Operator Ltd has become the organising centre of England’s passenger rail nationalisation programme, holding a growing set of operating companies while the sector moves towards a Great British Railways model. At the same time, devolved public operators in Scotland and Wales remain outside that structure, and privately run open access and freight operators remain permanent features of the network. The result is a railway that may look broadly familiar to passengers day-to-day, yet is being reshaped behind the scenes through ownership transfers, new governance bodies and a reworked balance between public control and regulated access for commercial operators.
Spain’s extensive rail network offers one of the most effective ways to explore the country without hiring a car. With high-speed services connecting major cities in hours, regional trains reaching smaller towns and well-integrated suburban networks supporting day trips, the system rewards careful planning with straightforward city-centre to city-centre travel and access to diverse landscapes from Andalusian heritage sites to Pyrenean mountain scenery.
Understanding the Network
High-Speed Services (AVE and Competitors)
The AVE (Alta Velocidad Española) network forms the backbone of tourist rail travel in Spain. Operating at speeds up to 310 km/h on standard gauge track, these services have transformed domestic travel since 1992. Spain now operates the second-largest high-speed network in the world after China, with approximately 3,900 kilometres of track.
Key high-speed corridors include:
Madrid to Barcelona: 2 hours 30 minutes via Zaragoza
Madrid to Seville: 2 hours 30 minutes via Córdoba
Madrid to Valencia: 2 hours via Cuenca
Madrid to Málaga: 2 hours 40 minutes via Córdoba and Antequera
Barcelona to Seville: 5 hours 48 minutes (direct service launched April 2025)
Since 2020, Spain has opened its high-speed network to competition. Alongside state-owned Renfe’s AVE and budget AVLO services, private operators Iryo and Ouigo España now run trains on major routes. This typically means more departure times and competitive fares, though it requires checking which operator your ticket is with and understanding their specific conditions.
Conventional Long-Distance Services
Beyond the high-speed network, Renfe operates conventional long-distance trains serving cities not connected by AVE. These services, many running on Iberian gauge (1,668mm) rather than standard gauge, operate at lower speeds with more modest frequencies. They become particularly relevant for reaching destinations in northern Spain and some parts of Andalusia where high-speed infrastructure has not yet arrived.
Regional Services (Media Distancia)
Regional trains bridge the gap between high-speed corridors and local networks. They call at more stations, operate at moderate speeds and provide access to smaller cities and towns. Whilst slower than AVE services, they offer more relaxed, scenic travel through countryside and prove valuable for reaching places like Granada from Córdoba or Seville, or exploring coastal areas in northern Spain.
Commuter Networks (Cercanías)
Spain’s suburban rail services, branded Cercanías, operate in metropolitan areas including Madrid, Barcelona, Valencia, Seville and Bilbao. These frequent, affordably priced services prove particularly valuable for:
Reaching hotels in outer districts
Day trips to nearby towns
Connections between stations in large cities
Airport access (Madrid, Barcelona, Málaga)
Notably, long-distance tickets often include free Cercanías travel within three hours before departure and four hours after arrival in cities including Barcelona, Madrid, Seville, Valencia and Málaga.
The Core High-Speed Corridor
Madrid as Central Hub
Madrid Puerta de Atocha station serves as the primary hub for AVE services heading south and east, whilst Madrid Chamartín handles northern routes. A tunnel connecting the two stations opened in July 2022, though most tourist journeys still involve a single Madrid station.
Toledo makes an excellent day trip from Madrid using Avant high-speed services. The journey takes approximately 30 minutes, allowing an early start to explore the compact historic centre and evening return without changing hotels.
Andalusia
From Madrid, Seville is reached in approximately 2 hours 30 minutes on AVE services. This time saving matters practically, as it allows travellers to arrive with enough daylight to get their bearings and experience evening life rather than losing a full day to travel.
Córdoba sits 45 minutes from Seville by AVE, making it viable either as an overnight stop or a longer day visit focused on the Mezquita-Catedral and historic quarters. The city also connects efficiently to Málaga and Granada.
Granada requires more deliberate planning. Whilst connected to the high-speed network since the completion of the Granada to Antequera line, reaching it from Córdoba or Seville may involve regional services with different timetables than the main AVE routes. Visiting works best when Alhambra entry is booked well in advance, as tickets often sell out weeks ahead.
Málaga is reachable from Madrid in 2 hours 40 minutes, whilst Cádiz can be accessed via regional trains from Seville for those seeking a different atmosphere.
Barcelona Connection
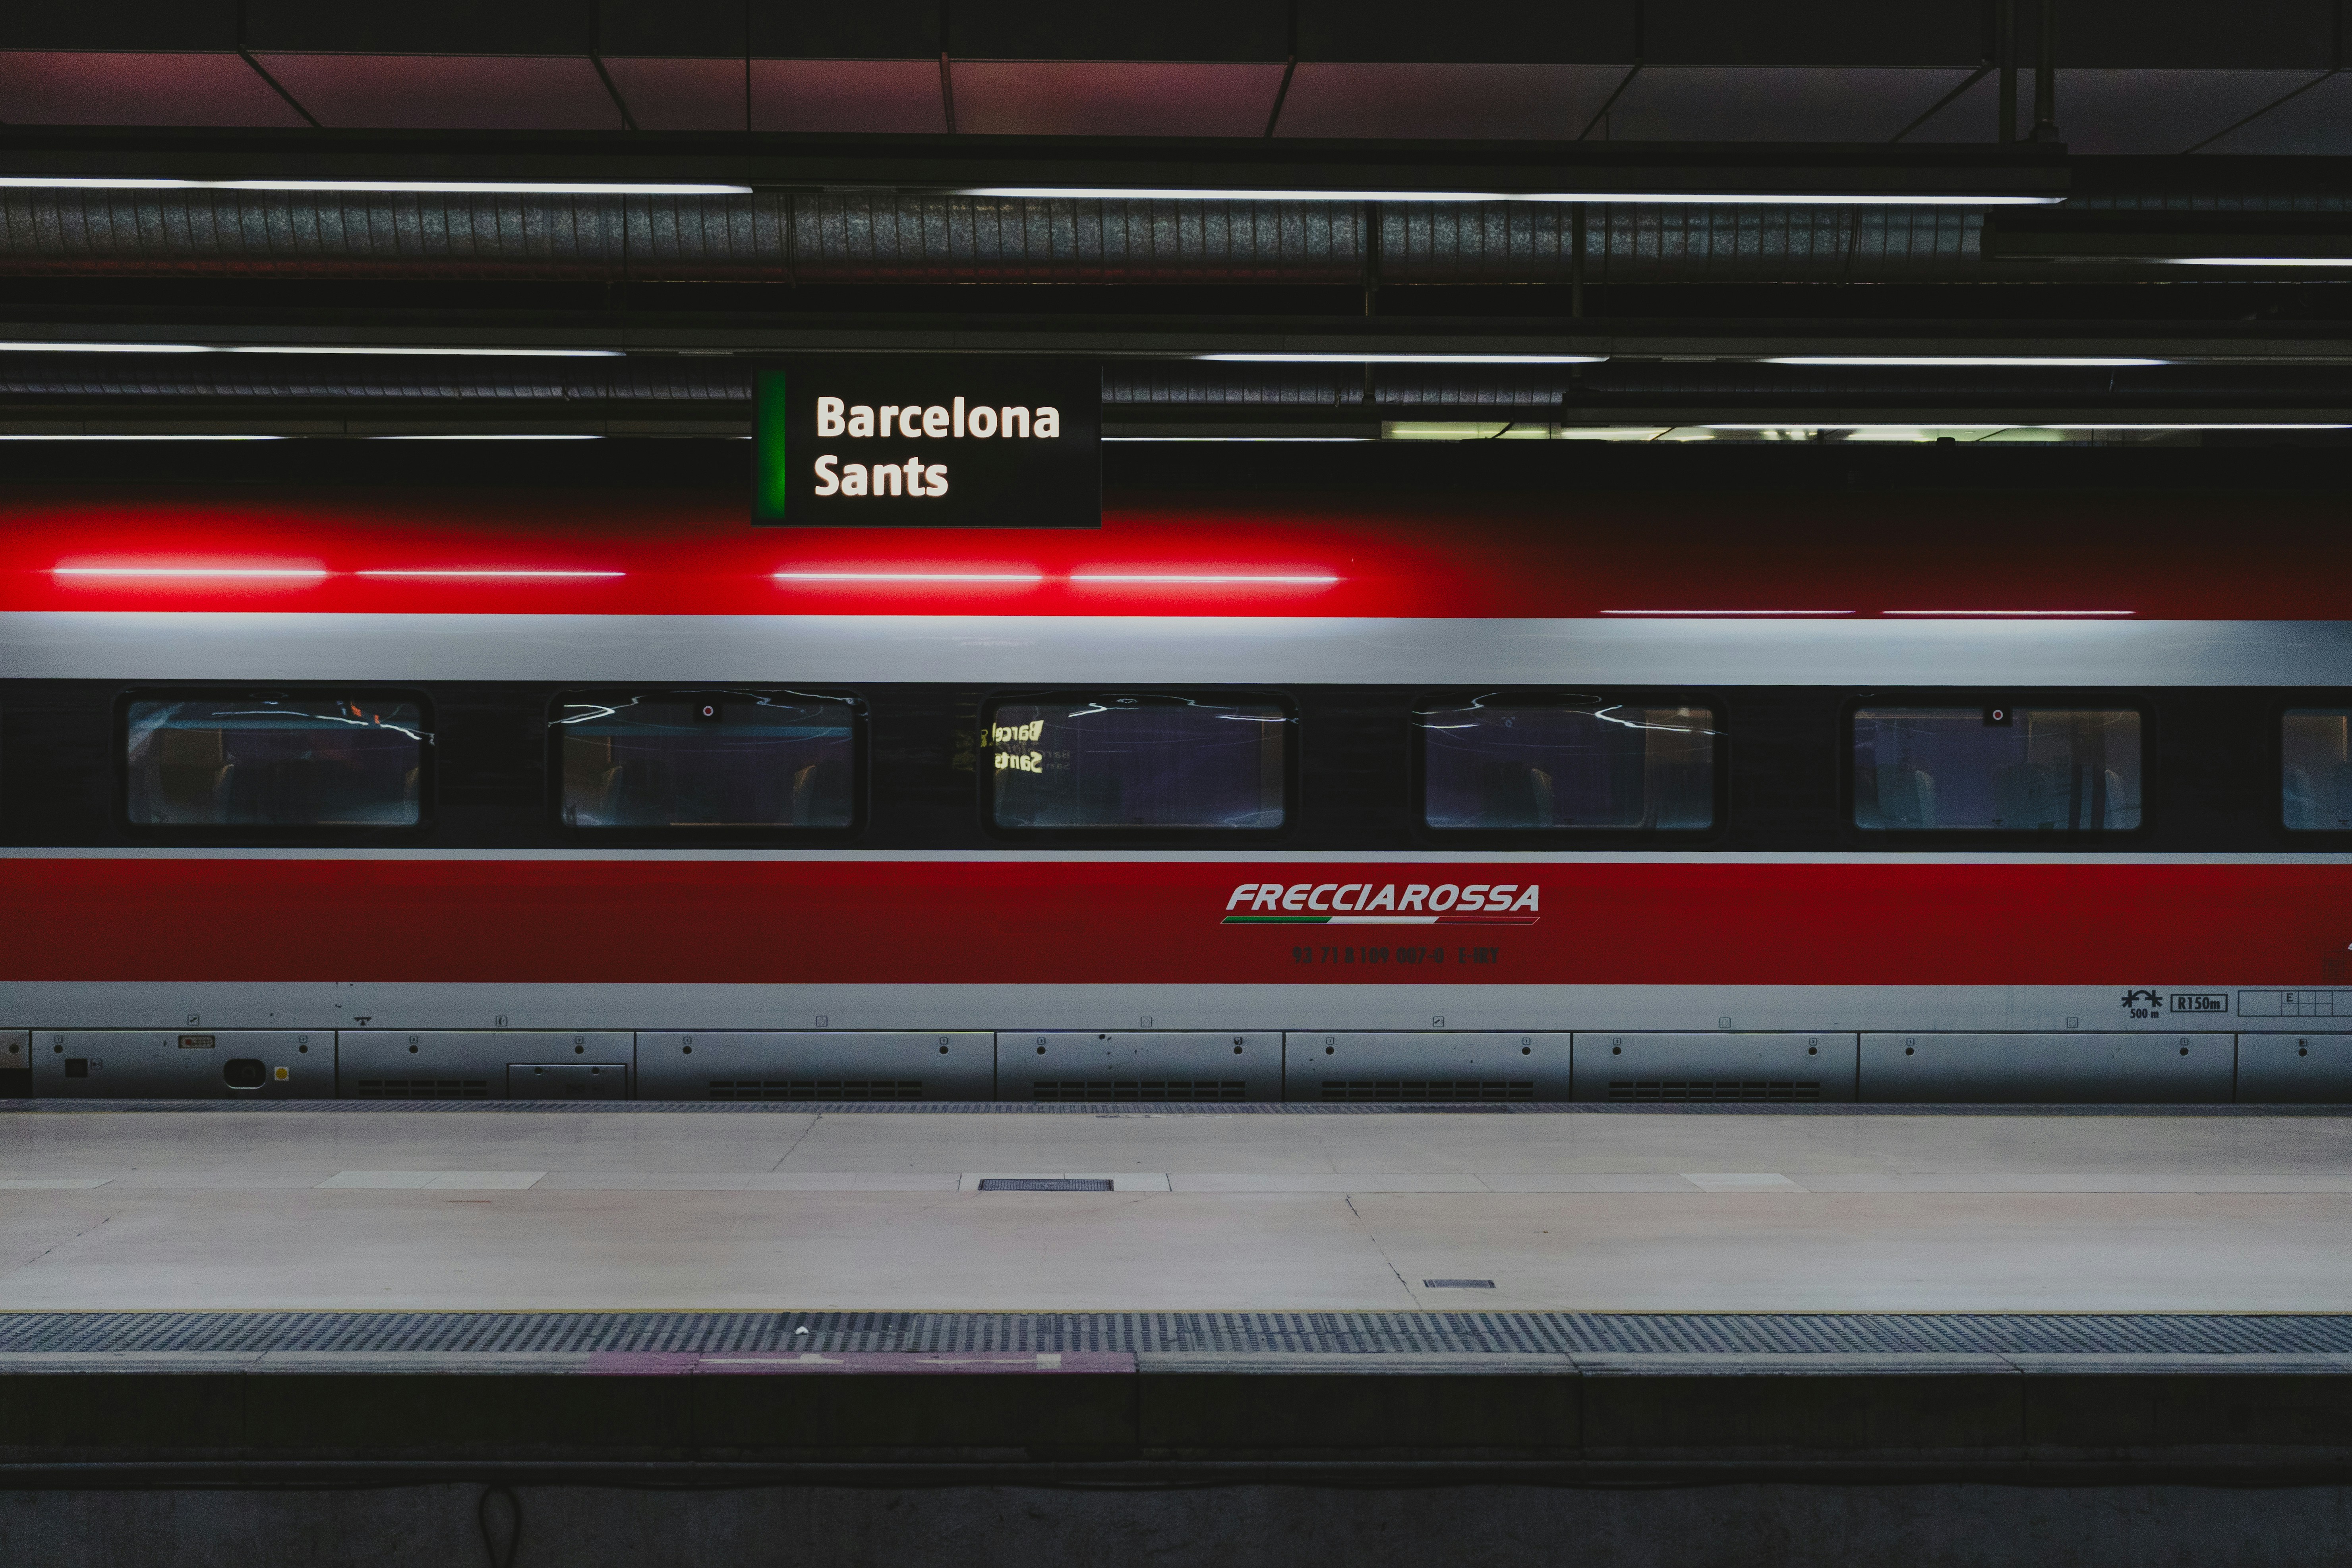
Barcelona can be reached from Madrid in 2 hours 30 minutes, or from Seville in under 6 hours on the direct service launched in April 2025. Barcelona Sants station functions as the city’s main interchange, with excellent metro connections to central districts.
Mediterranean Coast
Valencia sits 2 hours from Madrid on fast services, offering a base that combines an historic old town with the modern City of Arts and Sciences. Beach areas remain accessible via local transport rather than requiring a car.
From Barcelona, the coastal cities of Sitges (frequent regional trains, suitable for beach days) and Tarragona (40 minutes by regional or high-speed services, Roman heritage) provide straightforward day trips.
Barcelona Day Trips
Barcelona’s position makes it one of Spain’s most rail-connected tourist cities:
Montserrat: Combines a standard train with a rack railway or cable car for access to dramatic mountain scenery and walking routes
Girona: 40 minutes by high-speed services; medieval centre and city walls
Tarragona: Roman heritage by the sea, reachable by regional or high-speed services
Figueres: Home to the Dalí Theatre-Museum, with onward connections to France
Northern Spain (Green Spain)
Northern Spain offers a contrast to the centre and south with its Atlantic climate, greener landscapes and distinct regional character. Rail travel here is generally slower, and the network works best when travellers select a few bases rather than attempting to cover many places quickly.
Basque Country
The Basque region proves particularly rail-friendly. Bilbao and San Sebastián are connected by frequent trains, with the Euskotren coastal line between them offering slower but scenic travel. This service is often chosen because the journey itself becomes part of the experience rather than simply covering distance quickly.
Cantabria and Asturias
Santander in Cantabria serves as a stepping stone, though services can be less frequent and require careful timetable planning. Asturias, with bases such as Oviedo and Gijón, adds mountain scenery close to the sea and is notable for narrow-gauge coastal railways, including former FEVE lines. These routes prioritise scenery over speed, provided expectations about journey times remain realistic.
Galicia
Santiago de Compostela and A Coruña round off a northern journey. Modern trains link Galicia to Madrid relatively quickly, whilst local coastal exploration may require more patience, reflecting the general pattern where long-distance connections are strong, but some regional links remain slower.
The Pyrenees
The Pyrenees can be approached effectively by rail, particularly from Barcelona in the eastern section. The journey to Ribes de Freser followed by the rack railway to Vall de Núria provides one of the clearest examples of rail acting as mountain access rather than offering a dense network. It proves popular because it is reliable and does not require a car, allowing visitors to reach high mountain scenery, lakes and well-marked walking routes.
Cross-border options exist, such as travelling by regional trains to La Tour-de-Carol and connecting into France on scenic mountain lines, though these routes are slower and depend on careful timetable checking.
Central and western Pyrenees areas can be reached by rail in parts, but convenience drops and onward travel often shifts to buses. Rail-based Pyrenees trips work best as opportunities for day walks, mountain landscapes and cooler summer temperatures rather than as a means to hop between remote trailheads daily.
Practical Planning Principles
Advance Booking vs Flexibility
High-speed travel works best when booked in advance, as prices are lower earlier and reservations are mandatory. Tickets can be purchased through Renfe’s website, competitor operators’ sites, or agencies such as Rail Europe and Trainline.
Commuter services are typically more flexible for spontaneous use, suiting day trips and short hops within a region. Regional services fall between these extremes, benefiting from advance planning but usually offering places even on the day of travel.
Station Integration
Spain’s main stations are generally well-equipped and integrated with local transport. Madrid Puerta de Atocha, Barcelona Sants, Sevilla Santa Justa and Valencia Joaquín Sorolla all provide central locations, clear way finding, facilities such as cafés and shops, and connections to metro, buses and taxis. This station-to-station convenience is one of the main advantages of rail over driving, particularly where parking is limited, and historic centres have restricted traffic.
Service Frequencies
Where busy AVE corridors may offer multiple departures daily, some regional lines require timetable checking to avoid long gaps, particularly outside peak hours. This shapes what is realistic within a short itinerary: high-speed lines encourage ambitious multi-city plans, whilst conventional and regional networks tend to reward a slower rhythm and fewer base changes.
Strategic Base Selection
Rather than constant relocation, the network works best when travellers stay in a city such as Madrid, Barcelona, Seville or Bilbao, then use regional or commuter services for day trips. This approach reduces the exhaustion of checking in and out of hotels whilst still allowing substantial territory coverage.
Sample Frameworks
One Week: Classic First-Time Circuit
Focus on the strongest rail corridors:
Madrid (2 nights): Arrival, city orientation, possible Toledo day trip
Seville (2 nights): AVE from Madrid (2 hours 30 minutes), city exploration, possible Córdoba day visit
Barcelona (2-3 nights): AVE from Seville or via Madrid, city exploration, beach or mountain day trip
This framework keeps travel days manageable whilst covering three contrasting major cities with straightforward connections.
Two Weeks: Expanded Itinerary
Additional time allows either deeper exploration of existing bases or inclusion of further destinations:
Option A: Mediterranean Addition
Madrid (2-3 nights)
Valencia (2 nights): AVE from Madrid (2 hours)
Barcelona (3 nights)
Seville (2-3 nights): Direct AVE from Barcelona (5 hours 48 minutes)
Córdoba or Granada (1-2 nights)
Option B: Northern Contrast
Madrid (2 nights)
Seville (2 nights)
Barcelona (2 nights)
San Sebastián or Bilbao (3 nights): slower trains but different climate and culture
Return via Madrid or direct to airport
Option C: Andalusian Focus
Madrid (2 nights)
Seville (3 nights): with day trips to Cádiz or Jerez
The Spanish rail system’s main strengths for tourists remain consistent across regions. High-speed lines make long distances manageable, encouraging multi-city itineraries. Stations usually place travellers close to the places they want to visit. Commuter services help with day trips and local movement. Regional trains provide access to quieter towns and scenery at a calmer pace.
Limitations are equally consistent, particularly outside major corridors where service frequencies can be limited, and conventional rail speeds are markedly lower. For visitors, the solution tends to be advance booking for long-distance journeys, flexible planning around local trains and building itineraries around a handful of strategic bases rather than constant relocation.
Taken as a whole, Spain’s rail network offers a practical framework for everything from a fast-paced week linking Madrid, Andalusia and Barcelona to a slower two-week journey adding Valencia, Granada or northern Spain. With careful sequencing and realistic expectations about where trains are fast and where they are not, rail remains one of the most effective ways to see Spain without turning travel days into wasted days.
From October 25th, Bus Éireann is introducing revised timetables for its Expressway Route 13 and Route 14 services, which operate between Limerick, Tralee and Killarney. The changes aim to improve reliability and punctuality by adjusting departure times according to traffic conditions. A new Sunday morning departure from Tralee to Limerick has been added, and some weekday and Sunday journeys have been withdrawn. Discounted online fares are available until the end of November and customers are encouraged to book tickets in advance to secure their seats.
18:47, October 9th, 2026
The National Transport Authority, in partnership with Clare County Council, has introduced a new Ennis Town Bus Service, which will begin operating on 18th October 2026 as part of the Transport for Ireland network. The service includes two routes, NS1 and NS2, connecting key areas of Ennis such as the town centre, Ennis Hospital, Ennis Bus and Rail Station and surrounding residential areas. Both routes operate every 30 minutes throughout the day, with a 15-minute frequency along a shared central section and run from early morning until late at night.
The buses are low-floor, fully accessible and high capacity. Standard fares apply, with discounts available for Leap card users and free travel for certain groups. This development is part of the NTA’s Town Bus Programme, which seeks to provide sustainable and accessible public transport in regional towns across Ireland.
 Posted on April 11th, 2026